
Last updated: 2026-11-05
If you’re facing a sudden expense, a traditional payday loan can quickly become a trap. The interest rates are often so high that you’ll struggle to ever pay the full amount back. Finding a better way to bridge the gap between paychecks can save you hundreds of dollars in fees and interest.
1. Earnin
2. MoneyLion
3. Cortez Loans
4. OppLoans
5. NetCredit
6. FigLoans
When you’re looking at alternatives, cost and speed are what matter most. Some options are simple cash advances against your next paycheck, while others are more structured personal loans. It comes down to a choice: do you need a small amount of quick cash for a few days, or a larger sum to cover a major bill?
We looked at how each provider actually works as an alternative to high-interest payday loans. We focused on how fast you get the money, the maximum amounts available, and whether the service hits your credit score. You should always check if a service runs a hard FICO check before you commit to an application.
We also thought about who these services are actually for. Some platforms are built for people with steady jobs who just want to access their earned wages a few days early. Others cater to people with lower credit scores who need a more traditional loan structure to manage debt or a large, unexpected expense.
| Provider | Max Amount | Speed of Funding | Credit Impact | Primary Use Case |
|---|---|---|---|---|
| Earnin | see site | see site | see site | Earned wage access |
| MoneyLion | $100,000 | see site | Credit Builder Plus | Personal loans & cash advance |
| Cortez Loans | see site | see site | see site | Personal finance & advice |
| OppLoans | see site | Same-day funding available | Does not affect FICO score | Personal loans |
| NetCredit | $10,000 | Same-day funding available | see site | Personal loans & lines of credit |
| FigLoans | see site | see site | see site | Installment loans |
Earnin is for people who want to access the money they’ve already earned. Instead of taking out a loan that accumulates interest, you can “cash out” your wages before your scheduled payday. It’s a way to manage cash flow without getting stuck in a traditional debt cycle.
The service has a few extra tools, like “Balance Shield” to help protect your bank balance and credit monitoring to track your score. They also have “Savings Jars” if you want to set money aside from each paycheck. It’s a practical choice if you just need to bridge a short gap in your weekly budget.
Pros:
Cons:
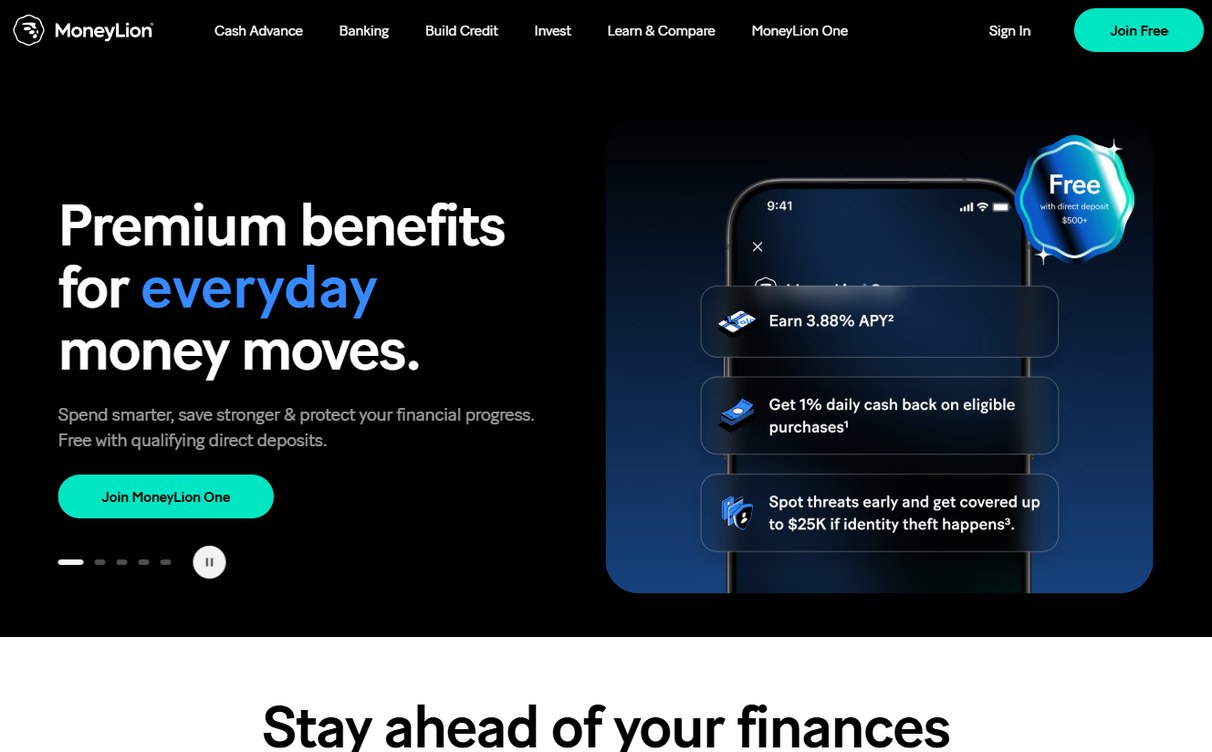
MoneyLion covers a lot of ground, from small cash advances to much larger personal loans. You can use Instacash for immediate needs or apply for a personal loan of up to $100,000 for bigger things like home improvements or paying off debt. They also have “Credit Builder Plus” to help people work on their scores.
The app is meant to be an all-in-one tool for managing your money. You can invest, build credit, and manage bills in the same place. If you’re in a rush, they offer expedited delivery, though you might have to pay a Turbo Fee for that.
Pros:
Cons:
Cortez Loans works differently than the quick cash advance apps. They focus on providing advice and information about personal finance, auto loans, and education. Their site is more of a resource for understanding tricky financial topics, like credit score ranges or how student loans affect mortgages.
If you’re searching for payday loan alternatives, their educational content can help you understand how different credit products actually work. They provide context on lifestyle changes and financial planning that might help you avoid high-interest loans altogether.
Pros:
Cons:
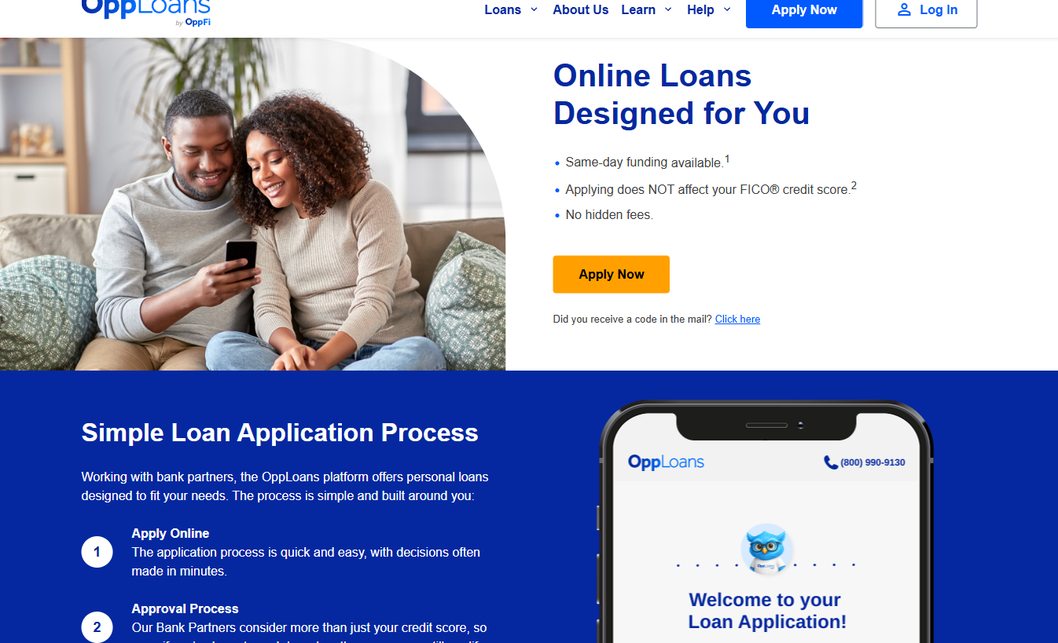
OppLoans is geared toward people who might have been turned down by other lenders. The application is quick, and you often get a decision in minutes. They use a process that looks at more than just your FICO score, which helps people with less-than-perfect credit.
One big plus is that applying doesn’t affect your FICO score. That’s helpful if you want to shop around for the best terms without hurting your credit. If you’re approved, you can get same-day funding in your account.
Pros:
Cons:
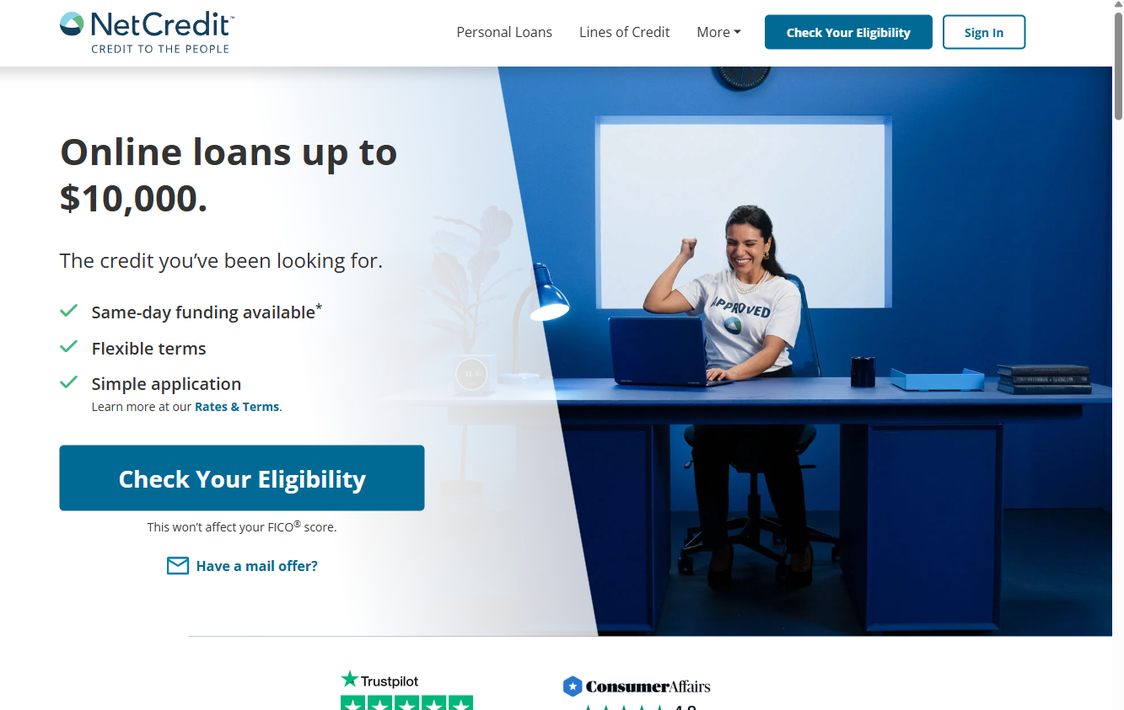
NetCredit offers personal loans and lines of credit for anyone wanting more flexibility than a standard payday loan. They offer loans up to $10,000 and have same-day funding available. They use advanced algorithms to look at your creditworthiness beyond a single score, meaning you aren’t just a number in a database.
The application is simple, and checking your eligibility won’t touch your FICO score. It’s a low-risk way to see what you might qualify for.
Pros:
Cons:
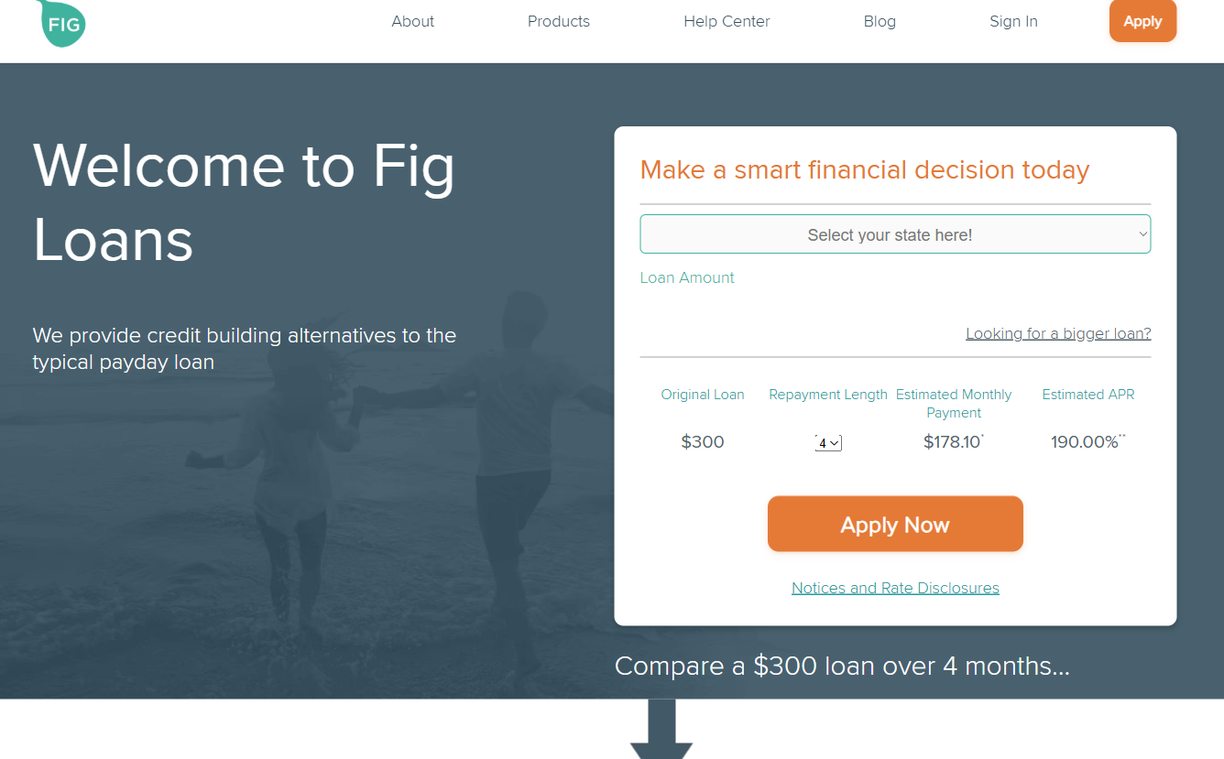
FigLoans specializes in installment loans. These are built as a direct alternative to payday loans because they spread payments out over time. For example, a $300 loan might be repaid over 4, 6, or 8 months. This makes the monthly payments a lot easier to handle than one giant lump sum.
They only operate in certain states, such as Texas, Ohio, and Florida. Since these are installment loans, they have a set repayment schedule and an estimated APR. Always check the specific terms for your state before you apply.
Pros:
Cons:
To pick the right one, figure out exactly how much you need and how long you need it for. If you just need $50 to get through the weekend, a cash advance app like Earnin is much cheaper than a loan. If you need $1,000 to fix a car, an installment or personal loan makes more sense. Cash advance apps are often the best way to avoid the massive costs of traditional payday lending.
A common mistake is ignoring the total cost of the loan. Always check the APR and the total amount you’ll have paid back by the end of the term. Don’t borrow more than you can afford to pay back in a single month, either. Even with an installment loan, a high monthly payment can land you right back in the debt cycle you were trying to escape. For more info on managing debt, you can read about alternatives to payday loans from various financial experts.